Choice Digital Launches the Choice Suite, Putting Payout Choice in Recipients' Hands

Learn more
Report · 

2026 State of Consumer Payout Preferences

Consumers evolved. Choice is now the only option.
2026 State of Consumer Payout Preferences_LP_628x652_01

2026 State of Consumer Payout Preferences

Take the PDF with you

Executive summary

Consumers carry their financial lives on their phones. They tap to pay, split a bill in seconds, and expect money the moment it's owed. But the way businesses send money hasn't kept up — and for the teams that own payout programs, the gap has become a measurable cost showing up in lagging engagement rates, support tickets, and even fraud exposure.

We surveyed over 1,500 U.S. adults who received a business payout in the past two years and analyzed redemption behavior across thousands of programs on the Choice Digital platform.

Together, they point to a single conclusion: Recipients want choice.

  • 94% of recipients say choice in payout method is important when receiving funds

  • 72% of recipients are more likely to choose a company that offers their preferred method

  • 68% of recipients are more likely to participate in a program when they can choose

That near-universal demand for choice is the part the industry already accepts. The harder question is what recipients do once they have it — and that's what this report answers.


Payouts are a recurring touchpoint

Payouts touch hundreds of millions of Americans every year — refunds, claims, reimbursements, deposits, rebates, incentives, settlements, and relief payments. 

  • 80% of recipients get payments more than a few times a year

  • 40% of recipients get one payment monthly or more often

The two most common are the ones companies most often treat as back-office overhead: 62% received a refund or deposit return in the past year, and 61% received an incentive or reward payout. More than a third (37%) received a claim or reimbursement, and 22% were paid through a marketplace or platform.

If a recipient engages with your payout process several times a year, the transaction becomes a relationship. And every payment either reinforces the impression that you're easy to deal with or chips away at it.

"The research tells us how much choice matters to people. Our platform shows what actually happens when they finally get it — and that's the part no one else can see."

 Theresa McEndree, Chief Growth Officer, Choice Digital


What recipients value most

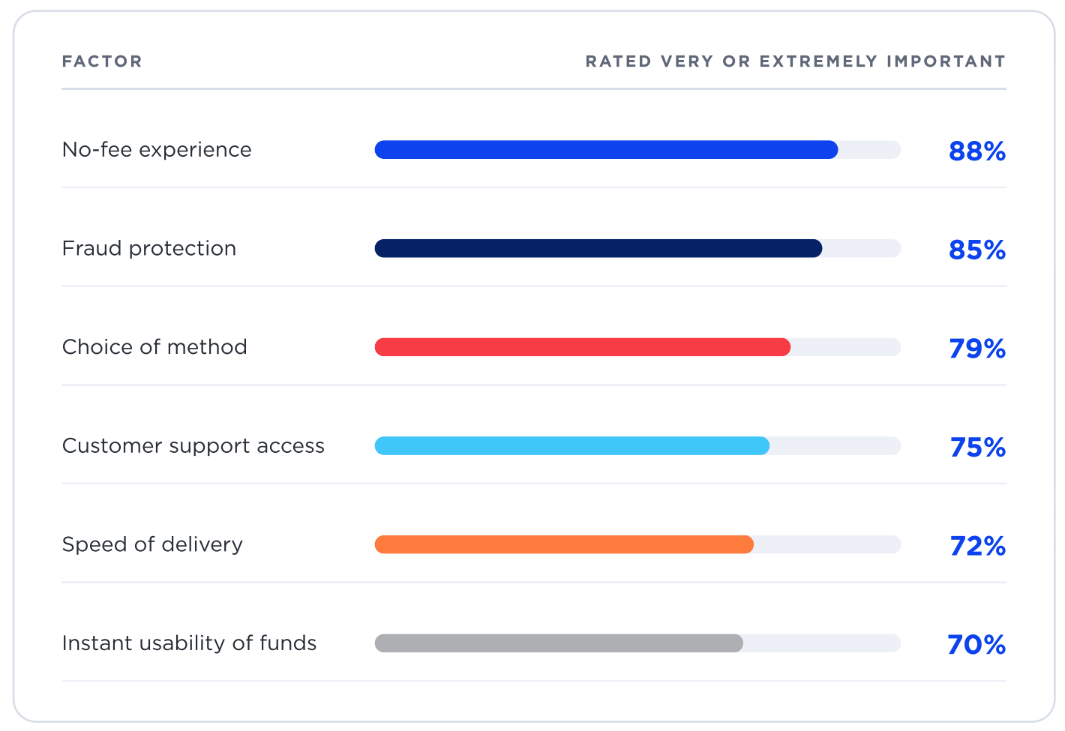
When recipients rank what matters when receiving a payout, choice is nearly at the top.

94% of recipients say choice in payout method is important when receiving funds — and for 79%, it matters a lot. No fees and fraud protection are the price of entry; then choice and speed are what turn an adequate payout into one people actively prefer.


How recipients choose to get paid

With Choice Digital, customers curate payout options around their program goals. And redemption behavior confirms that choice affects the outcome. 

Two approaches to the data make that clear: what happens when the payout amount changes but the menu doesn't, and what happens when the amount stays the same but the menu changes.

Same menu, four payout sizes

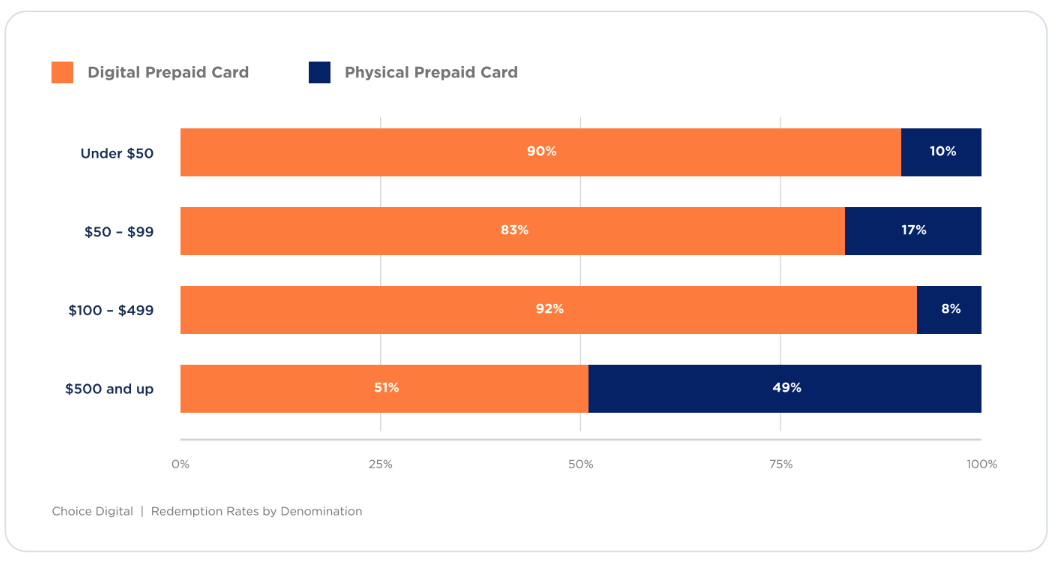
Here’s the share of disbursements by selected method for programs offering only digital and physical prepaid cards.

Offer digital and physical prepaid cards, and digital takes the majority of everything under $500. Then the payout crosses $500, and the split is almost half and half.

A digital-only default is right about 90% of the time for smaller payments, while physical becomes the preference as amounts increase. These are two different programs, and no single default gets both.

Same payout size, six different menus

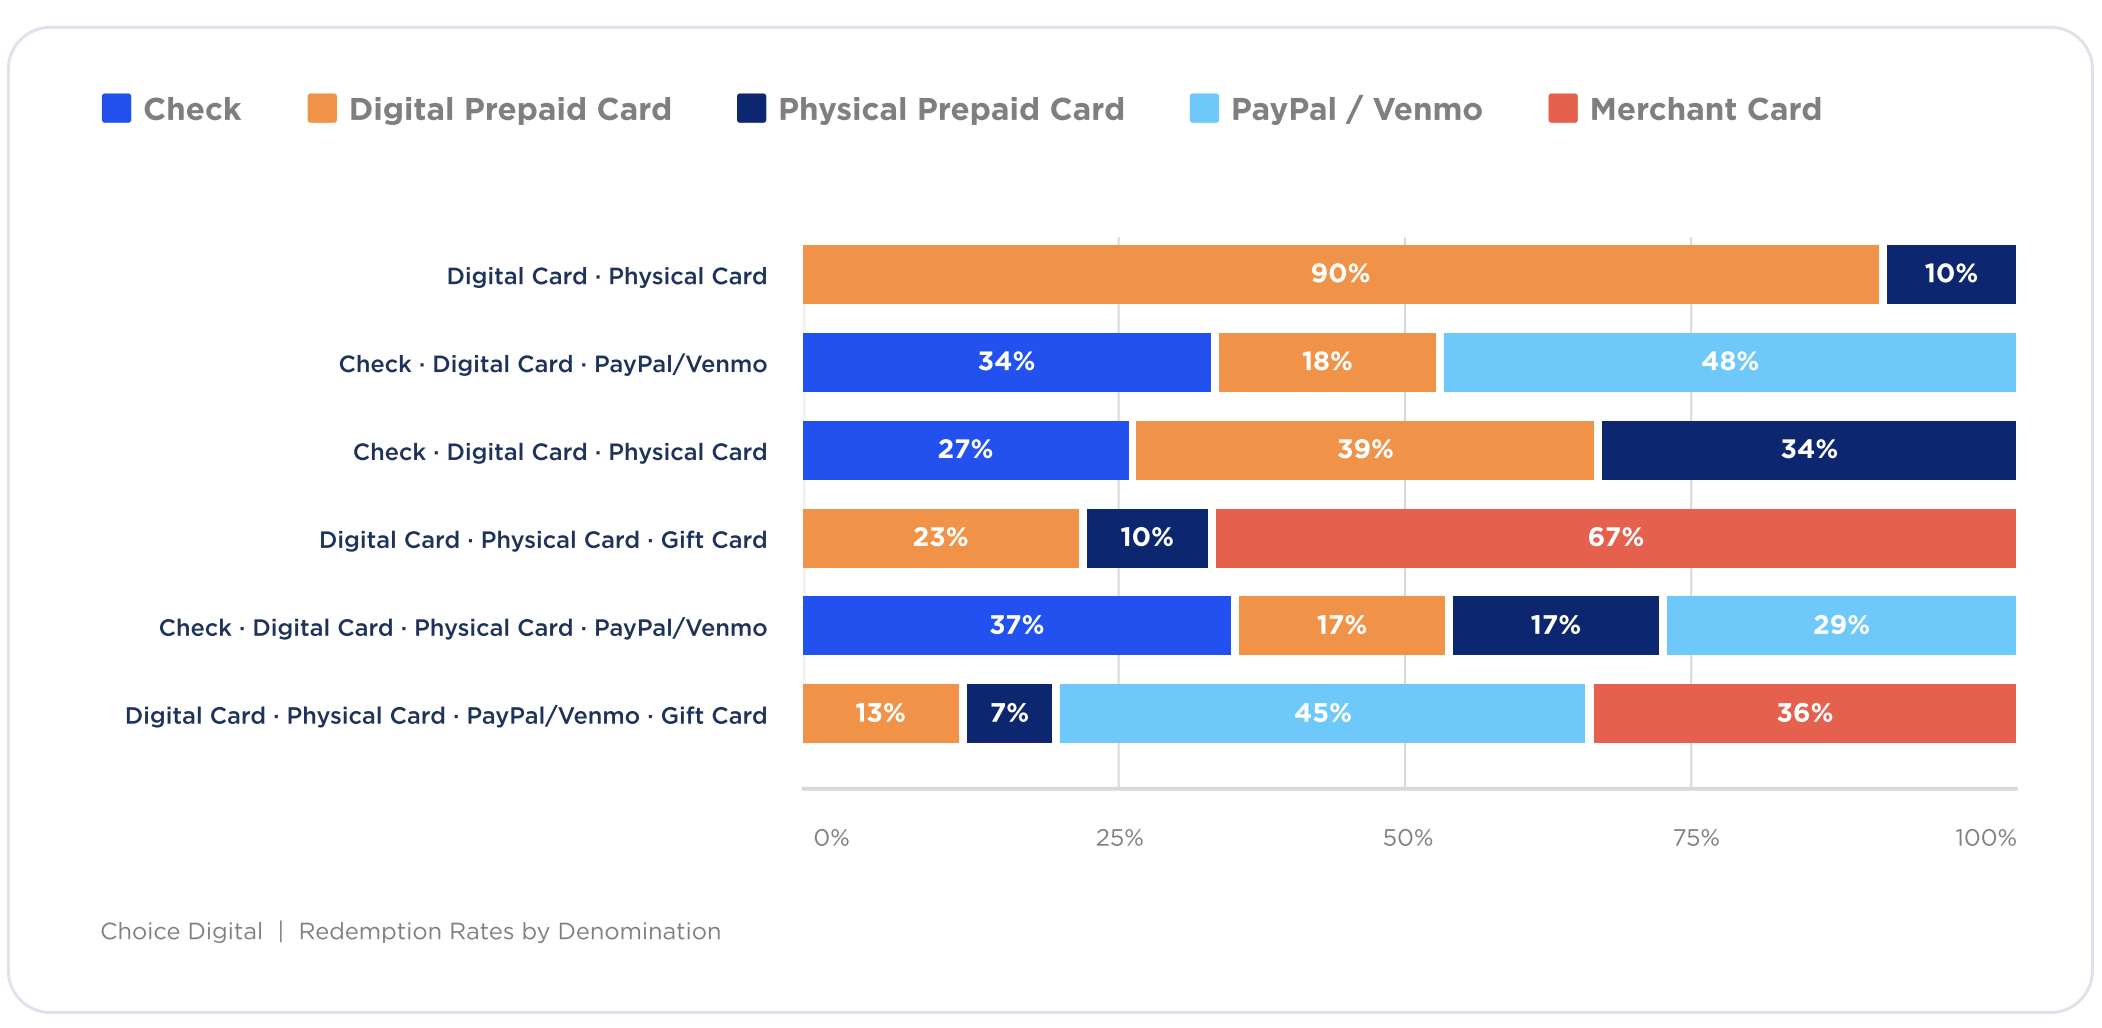
Now, let’s hold the payout range constant at <$50 and analyze the redemption changes by menu.

The results show that the number of choices can impact preference just as much as the choices themselves.

Digital prepaid takes 90% when it's only up against physical. Gift cards take 67% when it's only up against prepaid options. Add PayPal or Venmo, and the gift card falls to 36% while the wallet takes 45%.

Menu design is the lever

The paradox of choice states that too many options are paralyzing. Except in payouts, where recipients already know how they would like to redeem their money.

Which two or more options you offer depends on the payout amount and program goal participation, cost, satisfaction, reach. And most of the time, a program owner designing a menu for the first time is working from assumption, whereas a partner who has run thousands of these has the pattern.

Choice Digital sits across hundreds of regulated programs and can guide you on what would work best with your program goals and audience, so your menu is built on evidence rather than a guess you spend six months correcting.

"The right payout isn't a method — it's a match. Don't guess the one right method; design the right menu and let the recipient pick."

Mike Konrath, Chief Product Officer, Choice Digital


The impact of choice on brand perception

Getting the payout right doesn't just avoid a complaint. It changes how recipients see the company paying them.

  • 82% would be satisfied with a company that lets them choose

  • 74% are more likely to engage again with a company that offers payout choice

  • 72% are more likely to choose a company that offers instant payment options

  • 68% are more likely to participate in a promotion or rebate when they can choose how to get paid

  • 55% describe a company that pays instantly and digitally as convenient

  • 51% describe a company that pays instantly and digitally as customer-friendly

These are the compliments brands spend heavily to earn elsewhere. A payout earns them in a single interaction, because it's one of the few moments a company keeps a literal promise to a person.

The reverse is just as measurable. When asked what hurts trust in a payout, recipients named unexpected fees (70%), long delays (58%), fraud or security concerns (51%), friction accessing funds (42%), and no choice in payment method (39%).

And the gap is clear: 38% say their most recent payout was not the method they would have chosen. More than a third of payouts are landing as missed opportunities — and as an opening for a competitor who makes it easier.

There's a reach dimension too: One in seven recipients is underbanked and relying on check-cashing stores, money orders, or payday services, or holding no bank account at all. For them, a bank-transfer-only default doesn't just disappoint; it excludes.

Offering card, wallet, and digital options is how a program reaches everyone it was designed to serve.


The economics of getting it wrong

The recipient experience and the operating cost point in the same direction:

Checks are expensive and exposed

According to the Association for Financial Professionals (AFP), a single business check costs up to $4 to process before any fraud loss, and it's the most fraud-targeted payment method, with 58% of organizations hit in 2025. Not surprising, as it exposes a name, address, account and routing number, and a signature, then sends all of it through the mail.

And they create tedious, never-ending work

Checks have to be printed, mailed, and tracked manually. Some come back — wrong address, moved recipient — and get reissued. Some are never cashed at all, which means chasing recipients, then stop payments, then unclaimed-property filings under a different set of rules in every state.

Reconciliation happens weeks later against a bank statement rather than at the moment of payment, so a single payout can stay open on your books for months. And because a check in the mail has no status a recipient can look up, it becomes a support ticket on your end.

The cost lands on recipients, and they'll pay to escape it

The survey found that 28% of consumers paid a fee in the past year just to access money from a paper check — extra money your recipient spends to reach funds they've already earned.

Demand for speed runs the same way: 32% would pay a fee, at an average of $10, to receive their money instantly rather than wait two weeks. A striking willingness to pay for something a modern platform could deliver at no cost to them.

  • 58% say today's economy makes receiving money quickly more important

  • 57% say they'd be dissatisfied receiving a check in the mail instead of digitally

  • 47% say a two-week delay in receiving money would cause financial strain


The payout playbook

Four moves turn this research into a program recipients prefer, and a business case leadership can approve. None of them requires rebuilding your payout stack.

1. Add options to meet all needs

Not just more options — the right ones. As the platform data shows, a new method can have a significant impact. On small and mid-size amounts, recipients lean toward instant delivery. As sums grow, a digital wallet, like PayPal, can carry more of the volume.

How Choice Digital helps: every method sits in one catalog behind a single integration. From digital and physical prepaid cards to PayPal, Venmo, gift cards, push-to-card, ACH, and checks, adding the option that moves your volume is a configuration change.

2. Make trust visible before you make it fast

No surprise fees and fraud protection are what recipients rank as most valuable. Tell them the moment money moves — 53% would like to receive a notification via email and 42% by text. A payout they can't see the status of is a payout they don't trust yet.

How Choice Digital helps: identity verification, sanctions screening, and fraud protection sit inside the platform rather than in a separate risk stack, so the safest option is also the least work. Plus, digital notifications come with every payment, which means fewer "where's my money" tickets landing on your support team.

3. Let the method flex with the recipient and amount

Preference moves with the size of the payout. Digital prepaid takes 90% of choices under $50 and holds above 80% all the way to $499. Cross $500, and it drops to 51%.

Menu composition moves it too. A gift card takes 67% of under-$50 volume when it's up against digital and physical prepaid, and 36% when a wallet is added to that same menu. 

A single default can't follow either of these. A rebate program paying $25 and a claims program paying $900 are two different design problems even when they run on the same rails.

How Choice Digital helps: menus are configured per program, amount band, and use case from the same integration, so a rebate program and a claims program can run different menus without maintaining two systems. Reporting shows what recipients actually chose, so you can tune the menu on evidence instead of assumption.

4. Put your brand on the moment that matters

The options you offer shape what recipients choose. This is also where the payout stops being a cost line: 74% of recipients say they're more likely to engage again with a company that offered them a choice.

How Choice Digital helps: ChoiceCard, ChoiceWallet, and ChoiceLink carry your name through the payout itself, so the interaction builds the relationship rather than just closing a balance.

The reason most programs default to one method isn't that they think it's best. It's that every additional rail has historically meant another contract, another reconciliation process, another compliance surface, and another place for something to break. 

That's the constraint Choice Digital removes: one API, one funding flow, one reconciliation, one support model — with compliance and tax reporting handled inside the platform. Offering recipients real choice stops being an operational cost and becomes a setting you turn on.

"We're focused on the needs of consumer, brand, and customer. Choice Digital helps us meet those needs better than anyone else in market. By removing friction and increasing the ability to white-label the experience, together we bring the ideal recipient experience to market."

Bill Warshauer, Chief Revenue Officer, Tillo


Modern disbursements, delivered

The playbook is the same for every program. What it looks like in practice isn't. Some programs need one branded card. Some need a wallet that carries a relationship across years of recurring payouts. Some already know how each recipient gets paid and just need it to work.

The Choice Suite lets you deliver payments faster, safer, and smarter — at any scale. Every experience is fully branded, tracked in real time, and built on the same secure platform.

ChoiceCard

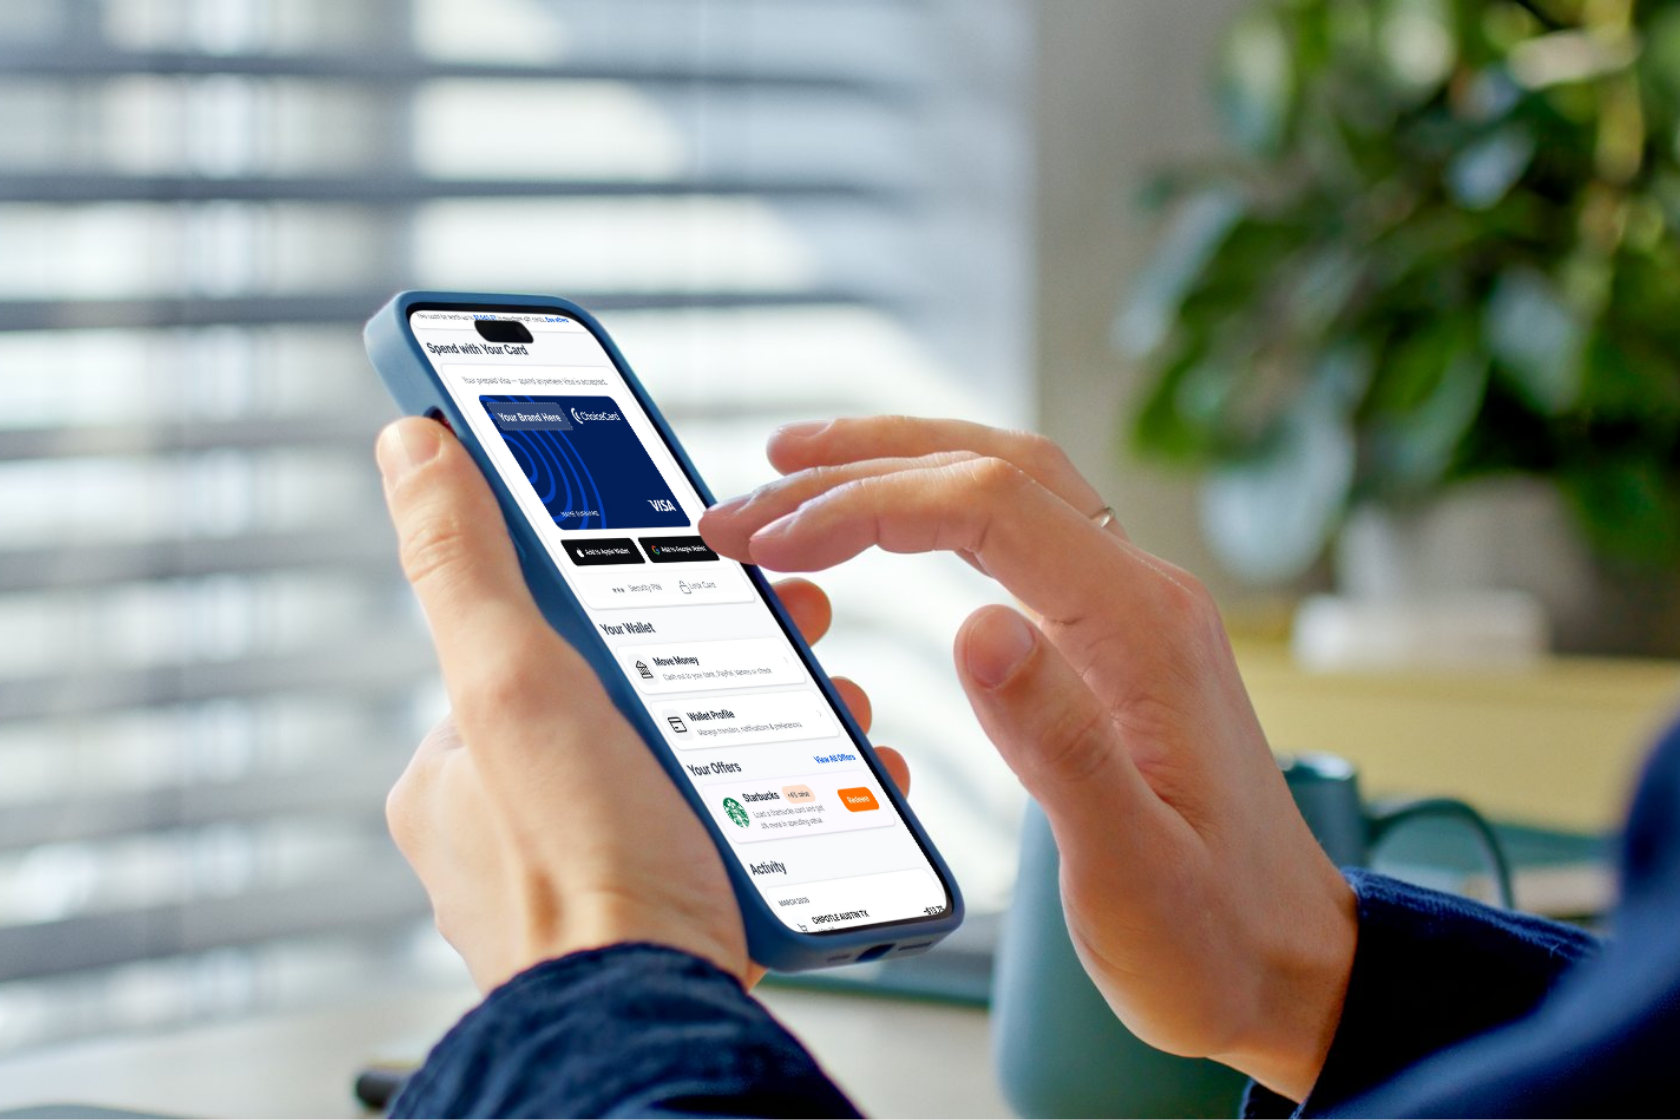
Physical or virtual, fully branded to your program, and ready for Apple Pay and Google Pay on arrival with no extra steps for the recipient. The fastest way to launch a card program that feels like yours. Learn more

ChoiceLink

One link delivers the full payout catalog: virtual prepaid card, physical prepaid card, ACH, PayPal, Venmo, gift card, or check. You control which options to offer. Learn more

ChoiceWallet

Built for recurring payouts. Recipients verify their identity once, and every future payment lands instantly. Since the wallet persists between payouts, it becomes somewhere recipients return to rather than a one-time transaction. Learn more

Choice is a strategy, and Choice Digital is how you run it. Book a payout strategy session


Methodology and sources

Survey: Survey of 1,567 U.S. adults (18+) who received a business payout in the past 24 months, fielded to a nationally representative sample of household decision makers. Percentages are calculated on how respondents answered each question.

Research: Choice Digital platform data covering thousands of disbursement and incentive programs, each one a method the recipient actively selected. Figures are averages across portfolios and do not represent a single program or client.

Informational only. Not financial or legal advice.

More to read